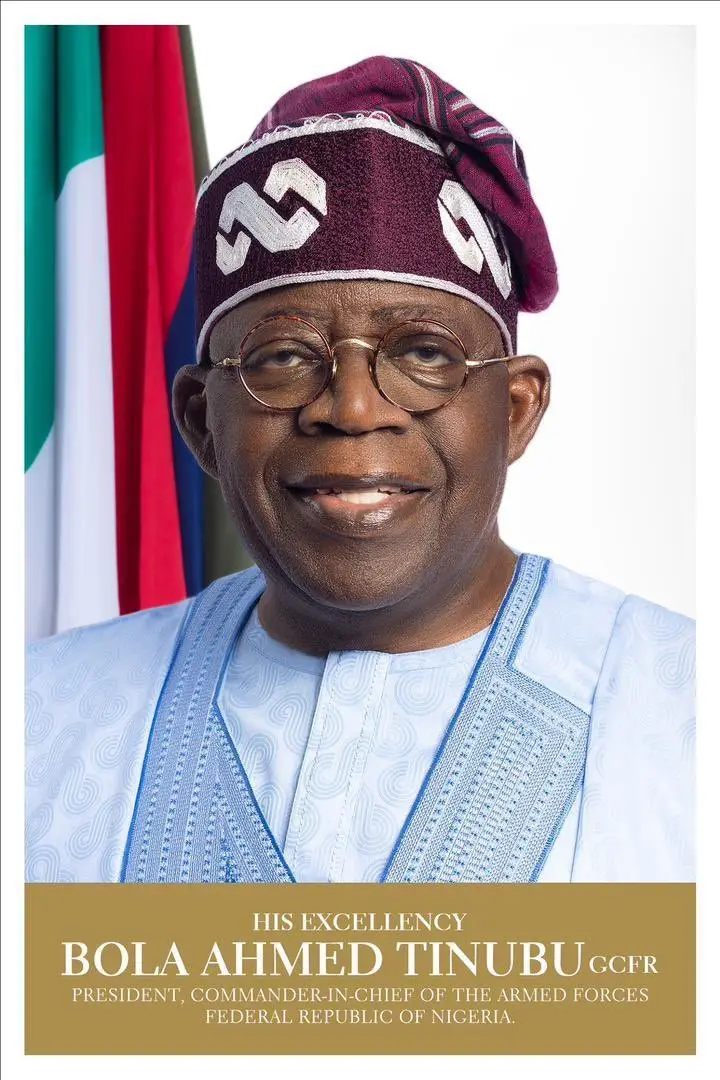
ABUJA, Nigeria (XOL Africa)— President Bola Tinubu has approved a new investment framework aimed at unlocking up to $50 billion in deep offshore oil and gas investment and reviving major projects that have remained stalled for years, the presidency said.
The reform replaces project-by-project negotiations with a rules-based system intended to provide greater certainty to investors and improve Nigeria’s ability to compete for international capital, according to a statement issued by Tinubu’s spokesman, Bayo Onanuga.
The framework, established through the Deep Offshore Oil and Gas Projects Incentives (Tax Remission) Order, 2026, is expected to support the development of a new generation of deep offshore projects, beginning with the roughly $10 billion Bonga South West development.
The measure follows Tinubu’s engagement with Shell Chief Executive Officer Wael Sawan, during which the president directed officials to develop measures to accelerate investment in Nigeria’s deep offshore sector, the statement said.
Rather than providing incentives for individual projects, the government developed a broader framework with eligibility requirements and implementation procedures that can apply to multiple qualifying developments.
The reform also allows NNPC Ltd., the government’s designated counterparty under production-sharing contracts, to make necessary amendments to eligible contracts to implement the new framework.
Olu Arowolo-Verheijen, Tinubu’s special adviser on oil and gas, said the policy was designed to ensure that increased offshore investment also generates greater economic activity inside Nigeria.
“Projects qualifying under the framework will maximise execution within Nigeria wherever commercially and technically feasible, strengthening domestic engineering, fabrication, marine logistics, technical services and project management,” Arowolo-Verheijen said.
“The objective is not only to increase investment and production, but also to create skilled jobs, deepen local supply chains and position Nigeria as Africa’s regional hub for deep offshore project execution,” she said.
The government said the framework was developed through an interagency process involving the presidency, fiscal and legal institutions, petroleum regulators and industry operators.
Tinubu commended the Federal Ministry of Justice, Federal Ministry of Finance, Federal Ministry of Petroleum Resources, Nigeria Revenue Service, NNPC Ltd., Nigerian Upstream Petroleum Regulatory Commission and Nigerian Content Development and Monitoring Board, as well as investors and other industry participants involved in developing the policy.
“The countries that attract long-term investment are not necessarily those with the greatest natural resources. They are the ones that provide the greatest certainty,” Tinubu said.
“This reform reflects our determination to build an investment environment defined by clear rules, strong institutions and enduring partnerships,” he said. “We are creating the conditions for capital to flow, for Nigerian businesses to grow, for our people to prosper and for our natural resources to deliver lasting national value.”
The government sees the reform as a way to revive capital-intensive offshore developments while increasing oil production, strengthening local industry and attracting long-term foreign investment to Nigeria’s upstream petroleum sector.
SUPPORT AFRICAN BUSINESS JOURNALISM
Help XOL Africa expand independent business reporting across Africa.
SUPPORT XOL AFRICA →